Best overall shortlist: Saudi National Bank. Best for international trade: Saudi Awwal Bank. Best for Islamic banking: Al Rajhi Bank. The best banks for business account opening in Saudi Arabia in 2026 depend on your ownership structure, payment needs and authorised signatories—not a promise of faster approval.
- The best banks for business account opening in Saudi Arabia depend on ownership, signatories and payment needs.
- Shortlist Saudi National Bank for broad corporate banking and Saudi Awwal Bank for international trade.
- Consider Al Rajhi Bank when Islamic banking is a selection requirement.
- Gofico supports foreign-company business setup and ongoing compliance; banks independently decide account applications.
Why this matters
A company registration does not replace a bank’s customer checks. Your bank must understand who owns and controls the company, what it does and how money will move through its account.
For foreign investors, banking belongs in the market-entry plan rather than at the end of it. Gofico supports business setup and ongoing compliance for foreign companies entering Saudi Arabia; account acceptance remains the bank’s decision.
Choose a bank that can support your operating model and assess your ownership structure. A familiar name alone does not answer either question.
What makes the best business bank in Saudi Arabia?
Use these criteria before choosing your 2026 shortlist:
- Ownership fit: Can the bank assess your foreign shareholders, ultimate beneficial owners and parent-company documents?
- Payment fit: Does the account support the domestic collections, payroll and international transfers your business needs?
- Signatory fit: What identification, residency, authority and attendance requirements apply to the people operating the account?
- Control fit: Can your finance team separate payment preparation, approval and account administration?
- Service fit: Which onboarding channel and escalation route serve your company type?
- Expansion fit: Can the bank discuss trade finance, treasury or financing needs as your Saudi operation develops?
Ask each shortlisted bank the same questions. Compare written answers against your actual requirements, not general statements about corporate banking.
Best Saudi business banks at a glance
These are purpose-led recommendations, not a ranking of approval rates or account-opening speed. Each bank makes its own eligibility and compliance decisions.
| Bank | Best for | Relevant service category | Key limitation to resolve |
|---|---|---|---|
| Saudi National Bank | Broad corporate banking requirements | Corporate banking, cash management and trade services | General service breadth does not establish eligibility for your ownership structure |
| Saudi Awwal Bank | Importers and exporters | Trade finance and international business banking | An operating account does not automatically include credit or trade facilities |
| Al Rajhi Bank | Companies prioritising Islamic banking | Sharia-compliant corporate banking | Each financing arrangement needs a separate suitability and eligibility review |
| Riyad Bank | Businesses planning financing discussions | Corporate banking and financing | Account opening and financing approval are separate decisions |
| Banque Saudi Fransi | Companies with treasury requirements | Corporate banking and treasury services | Specialist services require a separate discussion about access and suitability |
1. Saudi National Bank: best for broad corporate banking needs
Saudi National Bank, commonly abbreviated to SNB, provides corporate banking, cash management and trade services. It is a sensible starting point when your Saudi company needs to discuss several banking functions rather than only a current account.
Best for: Foreign companies seeking a broad corporate banking discussion during market entry.
Saudi National Bank pros:
- Corporate banking covers more than day-to-day account transactions.
- Cash management is relevant to collections and payment controls.
- Trade services provide a discussion route for importing and exporting businesses.
Saudi National Bank cons:
- A broad service range does not establish whether your specific entity qualifies.
- Account acceptance does not establish eligibility for borrowing or other facilities.
Ask the onboarding team which channel handles your legal form and foreign ownership structure. Confirm whether the proposed account supports your planned payment-authorisation process before completing the application.
Verdict: Shortlist Saudi National Bank as the default starting point for broad requirements.
2. Saudi Awwal Bank: best for international trade requirements
Saudi Awwal Bank, commonly abbreviated to SAB, offers corporate banking and trade finance services. It belongs on the shortlist when your Saudi operation will pay overseas suppliers, receive international customer payments or discuss documentary trade instruments.
Best for: Foreign companies whose Saudi operations involve importing or exporting.
Saudi Awwal Bank pros:
- Trade finance is an established service category.
- Corporate banking provides a route to discuss cross-border operating needs.
- Transaction banking services are relevant to recurring collections and payments.
Saudi Awwal Bank cons:
- A current account does not automatically include a trade finance facility.
- International transactions still require compliance checks and supporting information.
Describe your expected trade flows clearly: countries, counterparties, currencies and transaction purposes. Distinguish ordinary supplier transfers from requirements such as letters of credit, which need a separate assessment.
Verdict: Shortlist Saudi Awwal Bank when international trade shapes your banking requirements.
3. Al Rajhi Bank: best for an Islamic banking requirement
Al Rajhi Bank operates as an Islamic bank and provides corporate banking services. It is a relevant option when your company’s banking policy requires Sharia-compliant arrangements.
Best for: Foreign companies with an explicit Islamic banking requirement.
Al Rajhi Bank pros:
- Islamic banking is central to the bank’s operating model.
- Corporate banking serves business rather than personal account needs.
- Financing discussions can address Sharia-compliant structures.
Al Rajhi Bank cons:
- An Islamic banking preference does not resolve onboarding eligibility.
- Financing structures require their own commercial and contractual review.
Start with the operational account requirements, then discuss financing separately. Your finance and legal teams should understand any proposed arrangement rather than treating all business funding structures as interchangeable.
Verdict: Shortlist Al Rajhi Bank when Islamic banking is a defined selection criterion.
4. Riyad Bank: best for planning future financing discussions
Riyad Bank provides corporate banking and financing services. It is relevant when your Saudi company needs an operating account and expects to discuss working capital or other business financing as operations develop.
Best for: Companies planning a banking relationship that includes future financing discussions.
Riyad Bank pros:
- Corporate banking provides a starting point for business account enquiries.
- Financing services create a separate route for discussing funding needs.
- Cash management services are relevant to payment and collection processes.
Riyad Bank cons:
- Opening an account does not secure a financing commitment.
- A newly formed entity must distinguish projected activity from an established operating record.
Explain what you need immediately and what belongs to a later funding discussion. Keep the account-opening request clear rather than making it depend on financing that has not been assessed.
Verdict: Shortlist Riyad Bank when future financing is part of your banking plan.
5. Banque Saudi Fransi: best for treasury-led requirements
Banque Saudi Fransi provides corporate banking and treasury services. Include it when foreign-exchange exposure and treasury processes are material considerations for your Saudi business.
Best for: Companies whose finance teams need a dedicated treasury discussion.
Banque Saudi Fransi pros:
- Treasury is an established service category.
- Corporate banking supports discussion of operating account requirements.
- Foreign-exchange services are relevant to businesses with cross-border flows.
Banque Saudi Fransi cons:
- An account alone does not establish access to every treasury service.
- Complex treasury arrangements require a separate suitability and documentation review.
Explain which currencies your company receives and pays, and why. Keep routine currency conversion separate from any proposed hedging arrangement so the bank can assess each requirement accurately.
Verdict: Shortlist Banque Saudi Fransi when treasury needs influence the account decision.
How these banks were ranked
The ranking matches established corporate service categories to different business requirements. It does not claim measured differences in approval speed, customer satisfaction or acceptance rates.
For your 2026 decision, consult each bank’s official corporate banking information and confirm requirements directly with its onboarding team. Use the Saudi Central Bank, known as SAMA, for the regulatory framework—not a consultant’s statement about guaranteed acceptance.
Prepare your company before approaching a bank
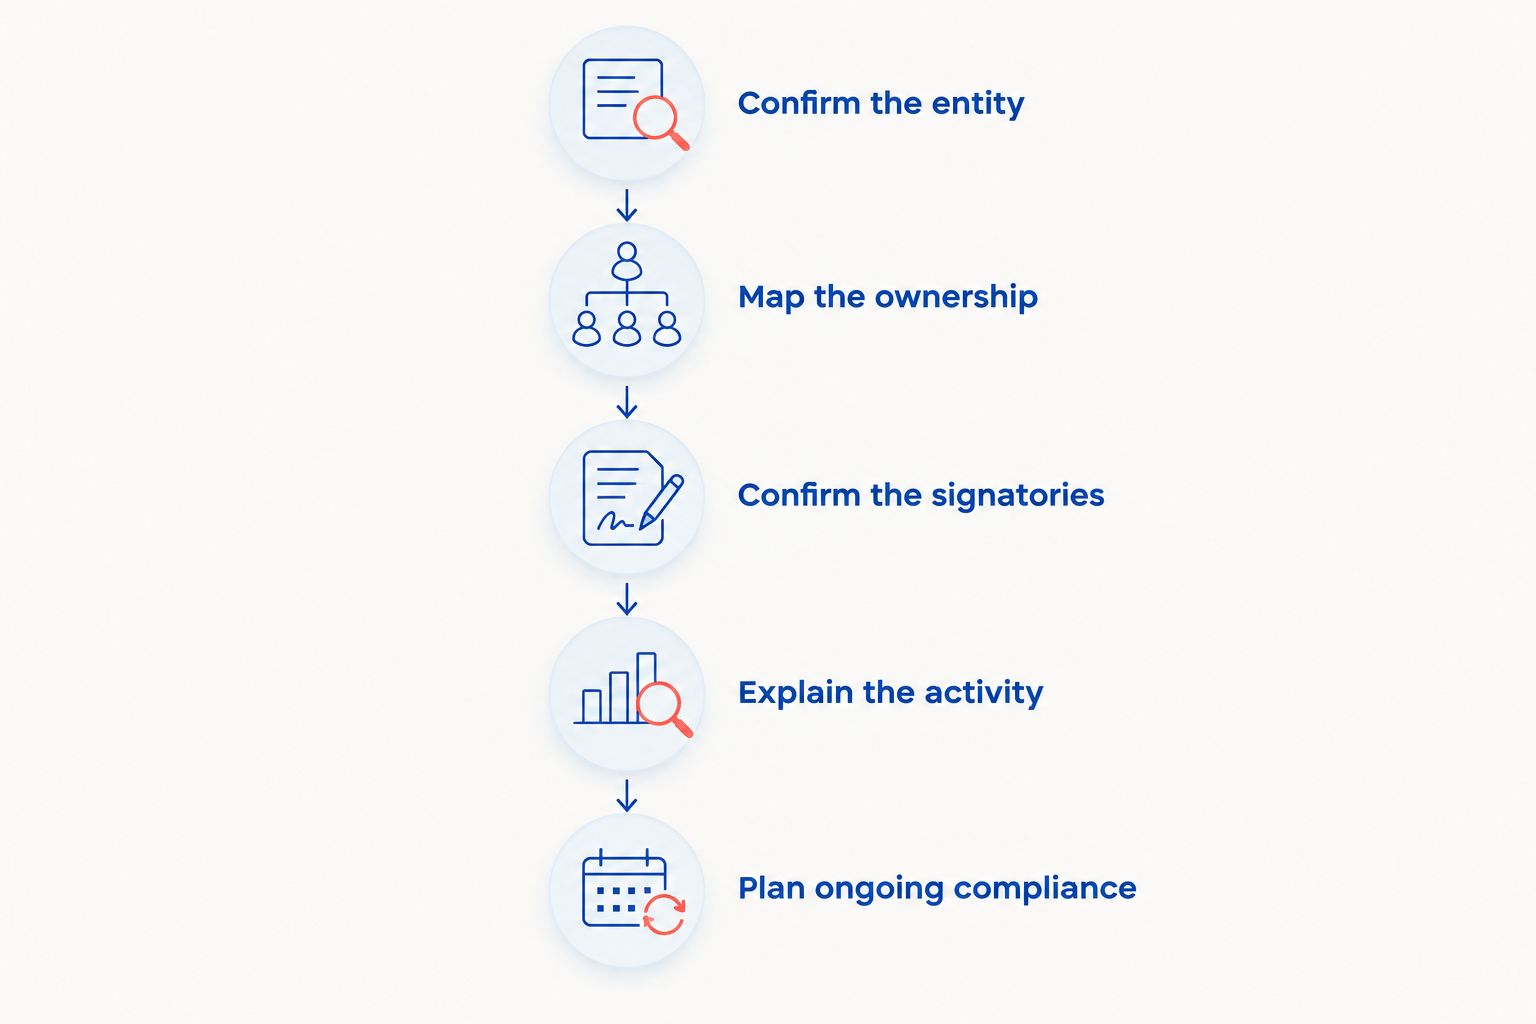
A useful application tells a consistent story across ownership, legal documents and expected transactions. Follow this preparation sequence before submitting sensitive documents.
Confirm the entity
Identify the Saudi legal entity that will hold the account and its permitted activities. Prepare its commercial registration—the official business registration record—and incorporation documents requested by the bank.
For foreign investment, confirm the applicable requirements with the Ministry of Investment, commonly known as MISA. Use its current 2026 guidance rather than assuming an older description of investment licensing applies unchanged.
Map the ownership
Prepare 1 ownership chart showing the chain from the Saudi entity to its ultimate beneficial owners: the individuals who ultimately own or control it. This is a preparation recommendation, not a claim that every bank accepts the same chart format.
Keep legal names and ownership information consistent across the chart and supporting documents. Explain intermediate holding companies instead of leaving the bank to infer their role.
Confirm the signatories
Ask what evidence the bank requires to establish each signatory’s identity and authority. Confirm any residency or attendance conditions before arranging travel or appointing someone solely for banking purposes.
If your internal policy requires 2 payment approvers, confirm that the proposed banking setup supports that control. Do not assume the signatory arrangement and online payment-approval arrangement are identical.
Explain the activity
Prepare a 12-month operating forecast covering expected collections, supplier payments, payroll and international transfers. Use it as an explanatory planning document, not as a substitute for the bank’s application forms.
State which figures are forecasts. Provide contracts, invoices or other commercial evidence when requested, and explain how expected transactions relate to the company’s registered activities.
Plan ongoing compliance
Keep ownership, address, signatory and business-activity information current after opening. Respond to requests for refreshed customer information and supporting transaction documents.
Banking also sits alongside employment, tax and corporate obligations. The business setup and compliance services offered by Gofico address initial formation and ongoing obligations; bank account approval remains separate.
Separate banking requirements from business setup services
A bank assesses the customer and decides whether to open the account. Government authorities determine registration and regulatory requirements; a business setup adviser supports the company’s preparation and compliance work.
Gofico is best suited to foreign companies seeking business setup support alongside ongoing compliance in Saudi Arabia. That positioning does not imply banking authority or guaranteed acceptance.
Keep government charges, bank charges and advisory services separate when assessing a proposal. Ask who performs each task, which authority or bank makes the decision, and which supporting documents remain your responsibility.
Before making a 2026 enquiry, prepare your ownership structure, proposed activities and expected transaction profile. Those details make the discussion more useful than asking only which bank opens accounts fastest.
Discuss your Saudi business setup
Explain your ownership, proposed activities and ongoing compliance requirements.
Which Saudi business bank should you choose?
Start with Saudi National Bank if you need a broad corporate banking discussion and have no specialist requirement. Choose Saudi Awwal Bank for a trade-led discussion, Al Rajhi Bank for an Islamic banking requirement, Riyad Bank for future financing discussions, or Banque Saudi Fransi for treasury needs.
Narrow the list to 2 banks and ask both to review the same factual company profile. This recommended shortlist size keeps the comparison focused; it is not a banking requirement.
Compare eligibility, required documents, payment controls and service scope before committing. For 2026 market entry, a suitable account is one your company can operate compliantly—not merely one that appears first in a ranking.
FAQ
What’s the best bank for a foreign company in Saudi Arabia?
Saudi National Bank is a starting shortlist choice for broad corporate banking requirements. Saudi Awwal Bank, Al Rajhi Bank, Riyad Bank and Banque Saudi Fransi suit different trade, Islamic banking, financing and treasury discussions. The bank must assess your company’s eligibility.
Can a foreign-owned company open a Saudi business bank account?
A foreign-owned Saudi company can apply for a business bank account, subject to the bank’s eligibility and compliance checks. Confirm requirements for the entity, ultimate beneficial owners and authorised signatories before submitting an application.
Which documents should I prepare for business account opening?
Prepare the company’s registration and incorporation documents, ownership information and signatory evidence. Banks also request information about business activities and expected transactions. Obtain the selected bank’s current checklist because requirements depend on the applicant.
Can I open the account without visiting Saudi Arabia?
Do not assume that a foreign company’s account can be opened entirely remotely. Ask the bank which identification, residency, electronic verification and attendance requirements apply to your entity and signatories.
Does opening a business account include financing?
No, opening a business account does not automatically include financing or trade facilities. Borrowing, guarantees and documentary trade arrangements require separate assessment and documentation.
Does MISA registration guarantee a bank account?
No, investment registration does not replace a bank’s independent customer checks. Confirm the applicable Ministry of Investment requirements for your business, then satisfy the selected bank’s onboarding requirements separately.
Can Gofico guarantee that a bank will approve my company?
No, the bank decides whether to accept an account application. Gofico provides business setup, compliance and consulting services for foreign investors and entrepreneurs entering Saudi Arabia.
One last thing
Ask how the account will handle a change of signatory before you appoint the first one. Your initial director or authorised representative might not remain in the role throughout the company’s life.
Confirm the bank’s update process and retain clear corporate authority records. Account maintenance deserves the same attention as account opening.
Related guides